The Real Question Behind a Tata Sons Listing
The debate is not simply about an IPO. It is about whether patient capital, stewardship and social purpose depend upon privacy, or can be protected through a different institutional architecture.
15 September 2026· 14 min read
TL;DR
The renewed debate over a potential Tata Sons listing, spurred by the RBI's rejection of its CIC status surrender, transcends a simple IPO. It ignites a fundamental question: does Tata Sons' cherished legacy of patient capital, stewardship, and social purpose inherently depend on privacy? Veteran director N.A. Soonawala warns that public listing risks compromising these foundational values, potentially shifting focus from long-term responsibility to immediate shareholder returns. This prompts a critical inquiry: can a new institutional architecture embrace transparency and public scrutiny without sacrificing its unique character? The RBI's decision underscores Tata Sons' systemic significance, challenging whether such an influential entity can truly remain private, thereby demanding a re-evaluation of its future.
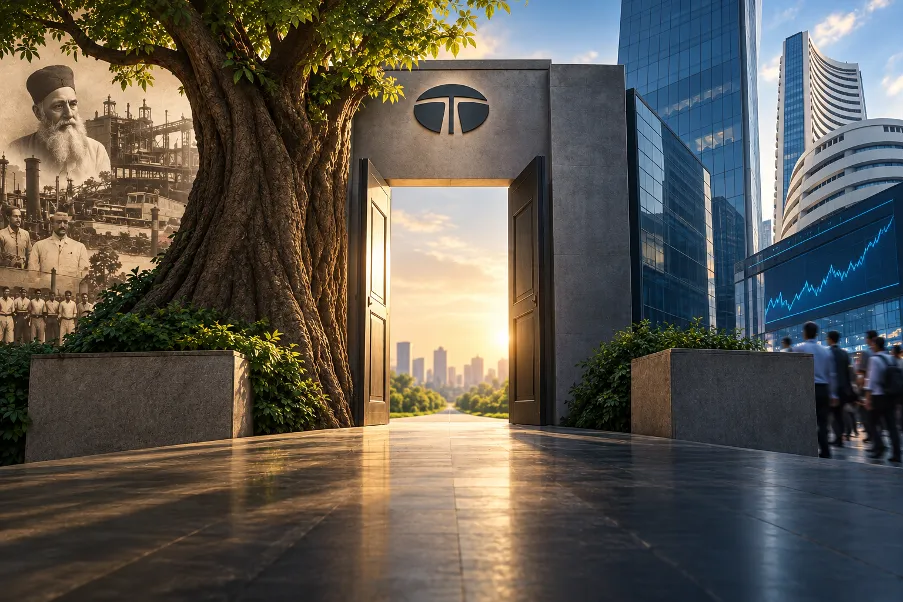
The reported decision by the Reserve Bank of India rejecting Tata Sons’ application to surrender its Core Investment Company registration has brought the prospect of a Tata Sons listing back into focus.
But the argument is being framed too narrowly.
This is no longer simply a debate about whether one of India’s most valuable companies should undertake an IPO. It is a collision between four different conceptions of Tata Sons: a private promoter company, the governing centre of a large corporate federation, the principal economic asset of charitable trusts, and a systemically significant financial holding company subject to public regulation.
At the heart of the debate lies a powerful intervention by N.A. Soonawala, the veteran Tata director and long-time adviser to successive Tata chairmen. His note arguing against listing deserves to be taken seriously because it articulates, with unusual clarity, the institutional case for keeping Tata Sons private.
Soonawala’s argument is not principally about valuation. It is about institutional character.
Tata Sons, in this view, is not merely a holding company whose worth can be calculated by adding up its investments. It has historically been the custodian of the Tata name, a source of patient capital, and, on occasion, the group’s insurer of last resort. Its decisions have sometimes been guided by reputation, responsibility and continuity rather than by the immediate financial return available to shareholders.
Listing, Soonawala warns, could alter the expectations, incentives and centres of influence surrounding those decisions.
That warning raises an equally important question.
Do the qualities worth preserving necessarily depend upon Tata Sons remaining private? Or is it possible to build an institutional architecture that accepts greater transparency and public scrutiny without sacrificing the longer purpose of ownership?
The RBI has changed the terms of the debate
Based on what has been reported so far, the RBI has rejected Tata Sons’ request to give up its status as a Core Investment Company (CIC). That means it will continue to face the tighter regulatory requirements that apply to Upper Layer NBFCs.
Tata Sons was placed in that category in September 2022, and the original three-year period for listing expired in September 2025. The precise RBI communication has not been made public. That matters because it would be premature to conclude that every possible option has disappeared. Tata Sons could seek reconsideration, challenge the decision, restructure parts of its operations, or negotiate the manner and timetable of compliance.
But the burden has clearly shifted.
Tata Sons had argued that it had become effectively debt-free after repaying substantial borrowings and no longer resembled the kind of financial institution the CIC framework was intended to regulate. The reported rejection suggests that the RBI is looking beyond the immediate balance sheet to economic substance: a holding company with assets exceeding ₹2 lakh crore, significant interests across major listed companies, investments in businesses that themselves employ public capital, and consequences extending well beyond its own shareholders to lenders, employees and strategic sectors.
The question the regulator appears to be asking is therefore larger than whether Tata Sons presently borrows from the public.
It is whether an institution occupying this position in India’s corporate and financial system can continue to be treated as entirely private in regulatory substance.
That is also why Tata Sons is entitled to make its own institutional argument. A regulatory category designed primarily for financial holding companies may not fully capture the character of a promoter and industrial steward whose responsibilities extend across enterprise, philanthropy and long-term nation-building.
The disagreement, then, is partly about regulation.
More fundamentally, it is about institutional identity.
What Soonawala gets profoundly right
Soonawala’s central insight is that Tata Sons is not an ordinary investment holding company. Historically, it has performed at least three roles simultaneously.
It has been the controlling shareholder and capital allocator of the group. It has acted as custodian of the Tata name and the behavioural expectations attached to it. And, at moments of crisis, it has acted as the group’s insurer of last resort—supporting Tata companies or honouring obligations where a narrowly financial shareholder might have preferred to contain losses.
That institutional capacity matters.
Tata Sons has sometimes been able to take decisions whose returns were reputational, systemic or intergenerational rather than immediately financial. A listed holding company subjected to continuous valuation, disclosure requirements and pressure from outside shareholders might find some of those decisions harder to make.
Soonawala is also right to question the assumption that listing would automatically “unlock” the enormous value embedded in Tata Sons. Listed holding companies can trade at substantial discounts to the value of their underlying assets. Investors may discount tax leakage, control structures, capital-allocation uncertainty and the limited influence available to minority shareholders. A Tata Sons quotation would create a visible market price and liquidity. It would not necessarily realise the very large valuations sometimes arrived at by simply adding up its underlying stakes.
But Soonawala’s more important point is not about the eventual share price.
Organisational form can shape institutional character. Once public investors enter Tata Sons, expectations change. Disclosure changes. Capital-allocation decisions acquire a new constituency. Decisions previously negotiated among a small and relatively stable body of shareholders would have to withstand scrutiny from investors who may have very different time horizons and objectives.
The risk, therefore, is not simply that Tata Sons might have to answer more questions. It is that the institution itself could gradually change—from the governing centre of a corporate federation into something increasingly judged as a portfolio of assets to be optimised.
That is a serious concern. And any argument for listing Tata Sons has to answer it.
But that does not settle the question. To see why, it is worth turning to the Tata group’s own history.
What Tata’s own history tells us about patient capital
The strongest case for the Tata model cannot rest on heritage alone. It has to be tested against what Tata stewardship has actually made possible.
Three episodes are particularly instructive because they represent three quite different judgements: when to protect, when to exit and when to persist.
In 1924, Tata Steel was facing a severe financial crisis. The company had embarked on a major expansion after the First World War, only to be hit by rising costs, weakening demand and falling steel prices. The crisis became so acute that there was a danger it would not be able to pay its workers.
Sir Dorabji Tata responded by putting his personal fortune behind the company. His assets, valued at about ₹1 crore and including Lady Meherbai Tata’s jewellery and the celebrated Jubilee Diamond, were pledged to the Imperial Bank to secure a ₹1 crore loan that helped Tata Steel through the crisis.
The story has understandably acquired an almost mythic place in Tata history. But stripped of the mythology, it tells us something important about patient ownership.
Tata Steel was already a public company. Dorabji himself owned less than a quarter of it. He was therefore putting additional private wealth at risk to preserve an industrial enterprise whose value, in his judgement, extended well beyond his own shareholding and beyond what the market could see at that moment.
With hindsight, that judgement looks remarkably farsighted. Tata Steel survived and became foundational to the group and to Indian industrial capability. But there could have been no certainty in 1924 that the company would eventually justify the capital and personal risk committed to saving it.
Patient ownership, in this instance, meant recognising that a crisis in price and liquidity was not necessarily a terminal failure of industrial purpose.
The journey from Lakmé to Trent illustrates a very different judgement.
By the mid-1990s, liberalisation had transformed the competitive landscape for cosmetics. Keeping Lakmé competitive against much larger global consumer companies would require substantial fresh investment, with no assurance of adequate returns. The Tatas chose to exit, selling the cosmetics business to Hindustan Lever.
What happened next is particularly instructive.
Lakmé was a listed company in which the Tata group owned only about 23.5%. The capital released by the transaction therefore did not belong to the promoter alone. When the Tatas subsequently considered merging the remaining Lakmé company with Indian Hotels, institutional and minority shareholders resisted. The proposed merger was dropped.
Market accountability had placed a boundary around promoter discretion.
But that constraint did not prevent strategic reinvention. The surviving company became Trent, entered organised retail, acquired the Indian operations of Littlewoods and launched Westside in 1998. A long period of experimentation and capability-building followed before Westside and, later, Zudio established Trent as a significant force in Indian retail.
The lesson is almost the reverse of Tata Steel.
Stewardship did not mean preserving Lakmé indefinitely because of its history within the group. It meant recognising when the economics had changed, releasing capital from one business and patiently building another.
Patient capital, in other words, is not passive capital.
Titan and Tanishq provide the third test: what happens when patience begins to look increasingly like persistence with a bad decision?
By the early 2000s, Tanishq had struggled for years and the future of the jewellery business was under serious question. Titan brought in McKinsey to examine the business and its portfolio. One of the questions put to the Tanishq team was stark: why should the jewellery business not be shut down?
The issue eventually reached Ratan Tata and the Titan leadership. Rather than impose a decision from Bombay House, Ratan Tata left the final call with Xerxes Desai and the Titan team.
They chose to stay with the business.
That decision matters because this was not simply a willingness to tolerate losses. Tanishq was changing its proposition as it learnt. It had misread important features of the Indian jewellery market, including consumers’ preference for higher-purity gold and the deep trust they placed in family jewellers. Titan adapted its offering and, through innovations such as the Karatmeter, turned purity and transparency into a source of competitive advantage.
Tanishq survived because it was learning.
Patient capital, in this instance, meant giving the business enough time to discover whether the underlying opportunity was sound, while remaining willing to change the model substantially.
And once again, this happened inside a listed company.
Titan’s public shareholders—and TIDCO, its public-sector co-promoter—remained invested through Tanishq’s long gestation and participated in the value eventually created. Public ownership did not prevent the Tata promoter from taking a long view.
But the episode also demonstrates the judgement patient ownership demands. There comes a point when every long-gestation investment must answer the question that McKinsey effectively put to Tanishq: why should we continue?
Taken together, the three episodes complicate any simple equation between privacy and patience.
Tata Steel was about protecting an enterprise through crisis. Lakmé–Trent was about knowing when to exit and redeploy. Titan–Tanishq was about giving a new business time to learn before deciding whether to persist.
Yet all three played out in the presence of public shareholders.
What the Tata system supplied was not immunity from markets. It was a stable, long-term steward capable of making different judgements at different moments: when to protect, when to exit and when to persist.
That leads directly to the harder question raised by the RBI decision.
What the Tata system supplied was not immunity from markets. It was a stable, long-term steward capable of knowing when to protect, when to exit and when to persist.
Does the long-term steward itself need to remain private?
That is where the Wallenberg system in Sweden provides an instructive, though imperfect, counterexample.
At its centre is Investor AB, established by the Wallenberg family in 1916 and today a publicly listed industrial holding company with significant stakes in businesses including Atlas Copco, Ericsson, Saab, SEB and AstraZeneca.
The resemblance to the Tata architecture is not exact, but it is instructive.
Investor’s largest owners are the Wallenberg Foundations, whose purpose includes supporting scientific research and education in Sweden. The largest of them, the Knut and Alice Wallenberg Foundation, held about 20% of Investor’s capital but nearly 43% of its voting rights in June 2026. Taken together, the three largest Wallenberg Foundations held 23.3% of the capital and 50% of the votes. Investor, meanwhile, had more than 745,000 shareholders.
The structure has allowed the Wallenberg sphere to combine stable control with outside ownership.
Investor describes itself not as a portfolio investor trading in and out of companies, but as an engaged, long-term industrial owner. It takes significant positions and works principally through the boards of its companies, involving itself in questions of strategy, capital structure, acquisitions, management and succession rather than their day-to-day operations.
At the same time, Investor is answerable to public shareholders. It explicitly seeks attractive shareholder returns, growth in net asset value and a steadily rising dividend. Those obligations have coexisted with an ownership philosophy measured across decades rather than quarters. Dividends flowing to the Wallenberg Foundations, in turn, help fund scientific research and education.
The comparison should not be pushed too far.
Swedish company law, the acceptance of differentiated voting rights and the historical development of the Wallenberg institutions differ materially from the Tata setting. Investor AB does not perform precisely the same integrative role across its sphere that Tata Sons performs within the Tata group.
But the example does challenge the strongest version of the argument for keeping Tata Sons private.
Public listing does not, by itself, make patient industrial ownership impossible. Nor must the entry of outside shareholders necessarily destroy the ability of a foundation-controlled institution to exercise long-term stewardship.
What listing changes is the architecture through which that stewardship operates.
Control has to be secured explicitly. The rights of outside shareholders have to be recognised. Capital allocation has to withstand scrutiny. And the holding company has to demonstrate that a long horizon is creating long-term value rather than simply insulating present decisions from challenge.
That may be the more useful lesson for Tata Sons.
The choice need not be framed as one between preserving the Tata model and submitting it to the market. The harder question is whether the characteristics worth preserving—patient capital, active stewardship, continuity of control and social purpose—can be embedded in an institutional structure robust enough to survive public ownership.
The deeper problem: can stewardship depend on the steward?
There is a deeper problem embedded in the argument for keeping Tata Sons private.
Stewardship, in this formulation, ultimately depends upon the judgement, wisdom and moral authority of those controlling the institution.
That worked exceptionally when authority, reputation and personal trust converged in figures such as J.R.D. Tata or Ratan Tata. Both were able to exercise influence that went well beyond the formal powers attached to their positions. Their personal credibility helped hold together a complicated federation of companies, executives, boards, shareholders and philanthropic trusts.
But an institution cannot permanently rely on the assumption that concentrated private power will always be exercised wisely.
That is not an argument against concentrated ownership. Stable controlling shareholders can provide precisely the long horizon that the Tata experience demonstrates is valuable. Nor is it an argument that public markets somehow eliminate personality, conflict or poor judgement. They plainly do not.
The question is whether the institutional architecture is strong enough when the exceptional steward is no longer there.
Privacy can support patience. It can create room for deliberation, continuity and decisions that cannot always be explained through quarterly metrics.
But privacy can also conceal disagreement, delay accountability and turn institutional questions into contests among personalities.
Recent tensions around succession, capital allocation, the newer businesses, the SP Group shareholding and relations within Tata Trusts illustrate the problem. The private structure has not eliminated short-term pressure, differences over strategy or political contestation. It has largely located them away from the public market.
The capacity worth preserving is not privacy for its own sake. It is the ability to take a long view.
The challenge facing Tata Sons is therefore larger than finding the next chairman capable of commanding the confidence of the Trusts and the board. It is to build an institutional compact that does not depend for its effectiveness upon the personalities occupying those positions at any particular moment.
This is where the distinction between stewardship and privacy becomes critical.
The capacity worth preserving is not privacy for its own sake. It is the ability to take a long view; to protect an enterprise when the evidence justifies patience; to exit when the economics have changed; to give a new business time to learn; and to allocate capital with a sense of responsibility extending beyond the next quarter.
The Tata cases suggest that these capabilities can coexist with public shareholders. Wallenberg suggests that even an apex industrial steward can combine stable foundation control with public ownership.
The harder task is to make those capabilities institutional rather than personal.
The social-purpose argument needs particular care
The strongest argument for keeping Tata Sons private may ultimately lie not in patient capital alone, but in the unusual relationship between enterprise and social purpose created by the Tata Trusts.
The Trusts’ ownership of about two-thirds of Tata Sons is genuinely distinctive. It changes both the ultimate destination and the time horizon of ownership. Commercial returns support further enterprise and flow towards public philanthropy, while stable control gives Tata Sons room to consider investments across generations rather than simply across reporting periods.
The Trusts do not make every Tata company a charity. Nor should social purpose become an argument for insulating commercial decisions from financial discipline. Tata companies must create customer value, allocate capital productively and remain economically viable.
What the Trusts provide is a societal horizon above those commercial enterprises.
There are legitimate reasons to fear that listing Tata Sons could gradually narrow that horizon.
Analysts may come to view Tata Sons principally through the value of its TCS stake, the holding-company discount, dividend yield and the performance of unlisted investments. Outside investors could press for higher distributions, fewer cross-holdings, the sale of assets deemed non-core, or shorter periods in which new investments must demonstrate acceptable returns.
What had been the governing centre of a corporate federation could gradually come to be understood as a portfolio awaiting optimisation.
That possibility should not be dismissed as an exaggerated fear of markets. Organisational forms create constituencies, and constituencies influence behaviour. Once outside shareholders own part of Tata Sons, their rights and economic interests would have to be taken seriously.
But the social-purpose argument runs in both directions. If the Trusts retain decisive ownership after a listing, they would continue to receive their proportionate dividends and participate in the long-term appreciation of the asset. Their philanthropic purpose does not disappear merely because a market price exists.
More importantly, the underlying capital-allocation tension exists already. The Trusts require reliable income to support philanthropy; Tata Sons may need to retain substantial capital for aviation, semiconductors, batteries and other long-gestation investments. Listing would make that tension more visible. It would not create it.
Because the Trusts hold one of India’s most valuable pools of charitable assets, decisions about Tata Sons cannot rest solely on inherited preference, institutional sentiment or the desire to preserve an existing arrangement. The trustees must be able to satisfy themselves that the ownership architecture they support—private or listed—best protects both the economic value of the assets entrusted to them and the purposes those assets exist to serve.
Founder intent matters enormously. But founder intent cannot simply mean preserving institutional form indefinitely.
Jamsetji Tata created institutions intended to serve the future. Fidelity to that inheritance may sometimes require protecting an established form. At other times, it may require adapting the form so that the purpose survives.
That is why the choice between privacy and listing cannot be reduced to one between social purpose and the market.
The real question is whether Tata Sons can accept a greater degree of external accountability without allowing the financial market to redefine what the institution exists to do.
The SP Group problem is not incidental
The SP Group shareholding brings another dimension to the debate.
The financial needs of one shareholder, even one holding 18.37% of Tata Sons, cannot be allowed to determine the constitutional future of the Tata group. On that point, Soonawala is right.
But the argument cannot end there.
An 18.37% holding is not incidental in any practical governance sense. It is an exceptionally large minority interest in an enormously valuable company for which there is presently no ready market.
The inability of Tata Sons and the SP Group to establish a mutually acceptable route to liquidity has persisted since the Mistry conflict. It has since become entangled with the SP Group’s financial requirements, share pledges, differences over valuation and restrictions surrounding the transfer of Tata Sons shares.
What may have begun as one shareholder’s liquidity problem has therefore become an unresolved institutional issue for Tata Sons itself.
Listing would not automatically solve it.
A large sale by the SP Group could create a substantial overhang and place pressure on the market price. Questions would remain about the timing and sequencing of any sale and the implications for Tata Sons’ ownership structure. Nor should an IPO be designed principally as an exit mechanism for one shareholder.
But listing would do two things that the present arrangement does not. It would establish a transparent market reference price and create a regulated route through which liquidity could develop over time.
If Tata Sons remains private, it therefore needs another credible and financeable mechanism through which the SP Group holding can eventually be resolved.
That could take different forms, and none is straightforward. The important point is not to prescribe one here. It is to recognise that “remain private” is not, by itself, a complete answer.
Privacy may be entirely defensible as an institutional choice.
Permanent illiquidity for an 18.37% minority shareholder is much harder to treat as an institutional design.
Listing and leadership succession now converge
The RBI decision has arrived at a particularly consequential moment for Tata Sons.
Questions about its regulatory status now sit alongside questions about leadership succession, the relationship between Tata Trusts and the Tata Sons board, the performance of major new investments, the future of the SP Group shareholding and the degree of strategic discretion that should rest with the executive chairman.
These issues are connected. But they should not be compressed into a single contest.
A change of chairman will not settle the regulatory question. Listing will not resolve choices about capital allocation. An SP Group exit will not define the appropriate boundary between the Trusts, the Tata Sons board and management. And concerns about the performance of Air India or newer investments cannot, by themselves, determine what Tata Sons’ ownership architecture should look like.
The danger is that decisions about all of them become entangled.
That would risk choosing a person before Tata Sons has settled the institution that person is being asked to lead.
The Tata system will inevitably continue to depend upon personal confidence. No governance architecture can eliminate the importance of trust between the Trusts, the board and the executive chairman.
But personal confidence now needs the support of a more explicit institutional compact.
That compact would need to clarify the respective roles of the Trusts, the Tata Sons board and management; the principles governing major long-horizon investments; the circumstances in which such investments should be reviewed or recalibrated; the route towards regulatory compliance; and an acceptable resolution of the SP Group shareholding.
The mandate should precede the choice of the person asked to carry it.
The next phase of Tata Sons will require two qualities that can easily be presented as opposites: the capacity for patience, and the capacity for challenge. Long-horizon investments need time. But they also need review points at which assumptions are tested and evidence reconsidered.
Patient capital and periodic challenge are not opposites. They are complements.
That principle should apply whether Tata Sons remains private, lists, restructures itself or reaches some other regulatory accommodation.
The durable course may therefore be neither categorical resistance to listing nor an exuberant “value-unlocking” IPO.
Any settlement will have to reconcile objectives that are too easily presented as alternatives: regulatory compliance and decisive Trusts control; public accountability and patient capital; commercial discipline and social purpose; a workable resolution of the SP Group shareholding and continuity in Tata Sons’ role as the governing centre of the group.
The precise architecture matters.
But what matters more is whether that architecture preserves the institutional capacities that made Tata Sons distinctive while reducing their dependence on personalities, private understandings and the assumption that the right steward will always be in the room.
The real question
The RBI decision has exposed a question that has been accumulating for decades.
What, constitutionally, is Tata Sons now?
If it is primarily a private promoter and custodian, the case for institutional continuity is compelling. If it is a financial holding company of extraordinary scale and systemic significance, the regulator’s demand for greater transparency is understandable. If it is the economic engine supporting public charitable trusts, both preservation and accountability matter. And if it is the governing centre of a federation containing some of India’s largest listed companies, its decisions already have consequences far beyond its own shareholder register.
That is why the argument has to move beyond listing versus no listing.
Tata history demonstrates the value of patient stewardship. But it does not demonstrate that stewardship requires privacy.
Tata Steel was public when Dorabji Tata put his fortune behind it. Lakmé and Trent were public when the Tatas exited one business and patiently built another. Titan was public while Tanishq struggled, learnt and eventually became one of the group’s most valuable businesses.
What those stories reveal is not the value of insulation from markets. They reveal the value of a stable steward capable of knowing when to protect, when to exit and when to persist.
That is the capacity Tata Sons needs to preserve.
Listing could weaken it if Tata Sons gradually becomes a portfolio judged principally by distributable cash, holding-company discounts and daily valuation. But privacy could weaken it too if institutional questions remain dependent upon personalities, informal understandings and mechanisms of accountability that have not kept pace with the scale and complexity of the institution.
The choice, therefore, is not between markets and stewardship.
It is about whether stewardship can be institutionalised strongly enough to survive either form of ownership.
Soonawala tells us what Tata Sons may lose if it lists. The RBI is effectively asking whether the present architecture remains adequate if it does not.
Tata Sons has to answer both.
And perhaps that is the real transition now confronting one of India’s most unusual institutions: not from private to public, but from stewardship resting substantially on history, relationships and exceptional individuals to stewardship embedded firmly enough in institutions to endure without them.
Join the conversation
Indrajit Gupta
Co-founder and Director | Founding Fuel
Indrajit Gupta is a business journalist and editor with over two decades of experience. He was the Founding Editor of the Indian edition of Forbes magazine. Within four years of its launch, Forbes India became the most influential magazine in its space.
He is the co-founder and director at Founding Fuel.
He has served in leadership positions at many of the leading media brands in the country. Before taking up the assignment to start up the India edition of Forbes magazine, Gupta was the Resident Editor of The Economic Times in Mumbai and before that, the National Business Editor of The Times of India.
Over the years, Gupta has built a reputation for grooming talent and creating highly energised and purposeful newsrooms. He has interviewed several leading global thought-leaders and business leaders including CK Prahalad, Ram Charan, Wayne Brockbank, Sumantra Ghoshal, Carlos Ghosn and Nitin Nohria, and also led cutting-edge joint research-based projects with McKinsey & Co, The Great Place to Work Institute, Boston Consulting Group, KMPG and Coopers & Lybrand.
He won the Polestar journalism award in 2010 and was awarded the Chevening fellowship by the British Foreign office in 1999. Gupta is an alumnus of the SP Jain Institute of Management and Research, Mumbai and a B.Com (Hons) graduate from St Xavier's College, Calcutta.
Gupta teaches a course on Business Problem Solving at his alma mater. He writes a column named Strategic Intent in Business Standard’s edit page. He lives in Mumbai with his wife and two young daughters.
Beyond the noise is the signal.
FF Insights: Sharpen your edge, Monday–Friday.
FF Life: Culture, ideas and perspectives you won't find elsewhere — Saturday.
Founding Fuel is sustained by readers who value depth, context, and independent thinking.
If this essay helped you think more clearly, you may choose to support our work.
Founding Fuel is sustained by readers who value depth, context, and independent thinking.
If this essay helped you think more clearly, you may choose to support our work.
Loading comments...


Readers also liked
·Artificial Intelligence
The Question AI Cannot Ask
The real advantage in an AI-driven world may not be answering questions better, but knowing which questions matter
AD

Anindya Dutta
Founder | Two Roads and author
The Question AI Cannot Ask
The real advantage in an AI-driven world may not be answering questions better, but knowing which questions matter
Founder | Two Roads and author

·Artificial Intelligence
The Knowledge Divide: How AI Will Reorganise Work, Margins, and Power
As AI agents embed intelligence into systems, the real shift is not automation—but how knowledge is owned, shared, and scaled across organisations
AB

DM

Arjo Basu & Debleena Majumdar
The Knowledge Divide: How AI Will Reorganise Work, Margins, and Power
As AI agents embed intelligence into systems, the real shift is not automation—but how knowledge is owned, shared, and scaled across organisations
Arjo Basu & Debleena Majumdar

·Work, Careers & Personal Mastery
Redesigning Work—or Retreating to Control
Why the real risk in the return-to-office debate isn’t resistance, but the quiet erosion of judgement and capability
KA

Kavi Arasu
Leadership and Talent Development Professional
Redesigning Work—or Retreating to Control
Why the real risk in the return-to-office debate isn’t resistance, but the quiet erosion of judgement and capability
Leadership and Talent Development Professional
Explore more
Dive into other themes from our network.